Comprehensive Insurance for Banquet Halls in India: Public Liability, Fire & Property Coverage (2026)
Co-Founder & CEO, Venura
Stop double bookings, manage hall calendars & automate GST bills.
Venura Venue OS unifies multi-hall booking calendars, token advances, and Tally Prime ledgers in real time.
Comprehensive Insurance for Banquet Halls in India: Public Liability, Fire & Property Coverage (2026)
The 5 Essential Commercial Insurance Policies for Banquet Venues
Comprehensive venue risk protection requires a multi-policy shield:
Covers legal liability and compensation claims arising from accidental third-party bodily injury, food poisoning, or property damage occurring on venue premises. Mandatory for hosting multinational corporate events.
Covers physical damage to the ballroom structure, false ceilings, acoustic wall paneling, and kitchen equipment caused by fire, lightning, electrical short circuits, explosion, storm, flood, and earthquake.
Covers theft of high-value venue assets—including P2.5 LED video walls, sound mixing consoles, HVAC chillers, and commercial kitchen equipment—following forcible entry.
Covers cash advances collected from wedding clients stored in the venue's commercial safe or in transit between the banquet office and bank.
Compensates for lost net profit and ongoing fixed overheads (staff salaries, bank loan EMIs, property lease) during mandatory repairs following a covered fire or flood incident.
Venue Insurance Policy & Premium Benchmark Matrix
The table below outlines recommended coverage limits and estimated annual premiums for a 500-capacity banquet property in India:
| Insurance Policy Type | Recommended Sum Insured | Estimated Annual Premium | Critical Risk Covered |
|---|---|---|---|
| Public Liability (Industrial / Non-Industrial) | ₹5,00,00,000 (AOA / AOY 1:1) | ₹25,000 – ₹45,000 / year | Guest slip-and-fall, food poisoning, stage collapse |
| Standard Fire & Special Perils (Building + Assets) | ₹3,50,00,000 (Reinstatement Value) | ₹35,000 – ₹65,000 / year | Fire short circuit, kitchen explosion, flood damage |
| Burglary & Housebreaking Policy | ₹50,00,000 (Electronic & AV Assets) | ₹12,00,000 / year | Theft of sound mixers, LED walls, kitchen equipment |
| Plate Glass & Architectural Signage | ₹10,00,000 (Full Value) | ₹5,000 – ₹8,000 / year | Accidental breakage of grand glass facades & chandeliers |
| Money in Safe & Transit | ₹15,00,000 (Peak Wedding Season) | ₹6,000 – ₹10,000 / year | Theft of cash advances in office safe or en route to bank |
| Total Comprehensive Annual Shield | ₹9,25,00,000 Total Coverage | ₹83,000 – ₹1,40,000 / year | Complete balance sheet & personal asset protection |
Hawan Fire Safety & Open Flame Ritual Protocols
Hindu wedding rituals require sacred fire (Hawan / Pheras) inside the banquet hall. To prevent fire hazards and maintain insurance validity:
- Mandatory Fire Retardant Carpet Underlay: Install certified Class A fire-resistant mats under the wooden Hawan Kund platform.
- 10-Foot Clear Zone from Fabrics: Mandate a minimum 10-foot clearance between the sacred fire and fabric stage drapes.
- Dedicated CO2 & Water Mist Fire Extinguisher: Station a certified 4.5kg CO2 fire extinguisher and two water mist fire buckets directly behind the stage backdrop.
- Fire NOC Compliance: Maintain annual Fire Safety Certificates from your local Municipal Fire Department.
SOP for Handling On-Premises Incidents & Claims
If an incident occurs on venue premises, execute this 4-step claim protocol:
- 1Immediate Medical Assistance: Provide first aid from the emergency medical kit and transport injured parties to the nearest empaneled hospital.
- 2Photographic & CCTV Timestamp Evidence: Save 4K CCTV surveillance footage and capture high-resolution photos of the incident scene before cleaning.
- 3Formal Incident Log in Venura OS: Record the incident timestamp, witness statements, and affected guest details in your digital operations log.
- 4Notify Insurance Surveyor within 24 Hours: File an immediate formal claim intimation with your insurance broker to expedite surveyor inspection.
Plate Glass, Grand Chandeliers & High-Value Architectural Signage
Modern luxury banquet halls feature expansive structural glass facades, crystal chandeliers, and exterior neon signage:
- 1Plate Glass Comprehensive Endorsement: Covers accidental fracture of structural glass panels, grand entrance doors, and floor-to-ceiling ballroom windows from high winds or crowd surges.
- 2Crystal Chandelier & Acoustic Panel Cover: Specifically schedules high-value crystal chandeliers (often worth ₹5L – ₹15L each) and acoustic fabric wall paneling against accidental dropping during truss rigging.
- 3Neon & Architectural LED Signage Policy: Covers external brand signage and digital billboards against electrical short circuits, lightning strikes, and storm damage.
Commercial Reinstatement Value vs Market Value Basis
When purchasing Fire & Special Perils insurance for banquet infrastructure:
- Reinstatement Value Clause (RVC): Always insure your ballroom structure, HVAC chillers, and interior acoustics on a Reinstatement Value basis rather than depreciated Market Value. This ensures the insurer pays the full replacement cost of brand-new equipment without deducting years of depreciation.
- Under-Insurance Penalty Prevention: Conduct an annual property valuation audit to ensure total sum insured matches current construction and replacement costs, avoiding proportional average deductions during claim settlements.
Interactive Booking Calendar & Conflict Simulator
Simulate live shift locking, double-booking prevention, and multi-hall booking in real time.
Pratham Shankwalker
Co-Founder & CEO, Venura
2nd-generation venue operator with deep operational experience managing 500+ capacity banquet halls, auspicious date shift scheduling, and municipal compliance across Indian wedding venues.
Common Operational Questions
Is Public Liability Insurance mandatory for banquet halls in India?
While municipal licensing rules vary by state, holding at least ₹2 Crores to ₹5 Crores in Public Liability Insurance is practically mandatory. Corporate clients, wedding planners, and municipal authorities require proof of insurance before authorizing high-capacity public gatherings.
Does commercial fire insurance cover damage caused by Hawan ritual fires?
Yes, provided the venue complies with basic statutory fire safety conditions (such as maintaining active fire extinguishers, functional smoke detectors, and a valid Fire Department NOC). Deliberate negligence or storing unauthorized explosives (firecrackers) inside the hall can void claims.
What is the difference between Any One Accident (AOA) and Any One Year (AOY) limits?
AOA is the maximum compensation the insurer will pay for a single accident/incident, while AOY is the cumulative maximum payout across the entire policy year. For banquet halls, an AOA:AOY ratio of 1:1 (e.g. ₹5 Cr AOA / ₹5 Cr AOY) is strongly recommended.
Can venue owners claim Input Tax Credit on insurance policy premiums?
Yes. Commercial insurance premiums attract 18% GST, which registered banquet hall operators can claim as 100% Input Tax Credit against their outward GST liability.
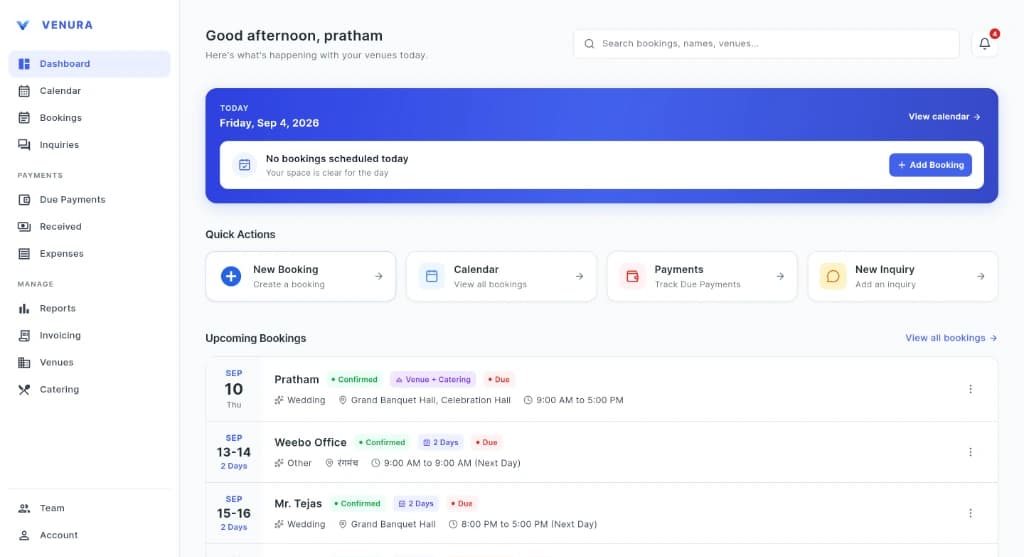
Put These Systems to Work in Venura Venue OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.