TDS on Banquet Hall: 2% (194C) or 10% Rent (194I), 2026
Co-Founder & CTO, Venura
Quick answer
TDS on a banquet hall booking is 2% under Section 194C (1% if the payer is an individual or HUF) when the hall supplies a package of hall plus food, as CBDT Circular 05/2002 treats it as a catering contract. Renting the hall alone, without food, is rent: 10% under Section 194I, but only when the rent paid by that client is more than ₹50,000 for the month. For payments from 1 April 2026 both sit in Section 393(1) of the Income-tax Act 2025, at the same rates. TDS is deducted on the value before GST.
- Hall plus food package
- 2% under Section 194C
- Hall rent only
- 10% under 194I, above ₹50,000 a month
- From 1 April 2026
- Section 393(1), Income-tax Act 2025
- GST component
- Excluded from TDS base
- Certificate
- Form 16A (Form 131 from tax year 2026-27)
TDS on Banquet Hall: 2% (194C) or 10% Rent (194I), 2026
On this page
Updated October 2026: new section numbers and the rent threshold
Two changes matter for every corporate booking in 2026:
- 1The Income-tax Act 2025 replaced the 1961 Act from 1 April 2026. TDS on contracts and on rent now sits in one place, Section 393(1), with the old sections mapped to rows of its table. The rates and thresholds were carried over, so a hall-plus-food package is still 2% and hall-only rent is still 10%. Accountants still say "194C" and "194I", so this guide uses both.
- 2Rent TDS now starts above ₹50,000 a month. Since 1 April 2025 the client deducts TDS on rent only when the rent it pays you is more than ₹50,000 for a month or part of a month. The old test was ₹2.4 lakh a year. A one-day hall booking of ₹40,000 therefore has no rent TDS.
Contract TDS (hall plus food) still applies when a single bill is above ₹30,000 or the client's payments to you pass ₹1 lakh in the year. The TDS certificate a client gives you, Form 16A, is replaced by Form 131 from tax year 2026-27.
| What | Income Tax Act 1961 (payments before 1 Apr 2026) | Income-tax Act 2025 (from 1 Apr 2026) | Rate |
|---|---|---|---|
| Hall plus food package (contract) | Section 194C | Section 393(1), Table Sl. 6(i) | 2% (1% individual or HUF) |
| Hall-only rent (land and building) | Section 194I(b) | Section 393(1), Table Sl. 2(ii) | 10%, above ₹50,000 a month |
| Rent of equipment (plant or machinery) | Section 194I(a) | Section 393(1), Table Sl. 2 | 2%, above ₹50,000 a month |
| TDS certificate to the venue | Form 16A | Form 131 | Quarterly |
Stop double bookings, manage hall calendars & automate GST bills.
Venura Venue OS unifies multi-hall booking calendars, token advances, and Tally Prime ledgers in real time.
The Statutory Legal Distinction: Section 194-I vs Section 194-C
Understanding the statutory Income Tax provisions for corporate event billing:
TDS Deduction Comparison Matrix across Corporate Booking Formats
The table below outlines TDS sections, rates, applicable SAC codes, and statutory documentation requirements across corporate event formats:
| Corporate Booking Format | Applicable SAC Code | Statutory TDS Section | Mandatory TDS Rate | Statutory Tax Document |
|---|---|---|---|---|
| Bundled Corporate AGM + Catering (500 PAX) | SAC 996331 | Section 194-C | 2.0% TDS (Company) | Form 16A / Form 131 (quarterly) |
| Pure Space Rental Only (Outside Catering) | SAC 997212 | Section 194-I | 10.0% TDS (Rent) | Form 16A / Form 131 (quarterly) |
| Day Delegate Corporate Training (DDR) | SAC 996331 | Section 194-C | 2.0% TDS (Company) | Form 16A / Form 131 (quarterly) |
| Preferred Vendor Stage Decorator Bill | SAC 998596 | Section 194-C | 2.0% TDS (Company) / 1% (Prop) | Form 16A / Form 131 (quarterly) |
| Preferred Vendor Commission Referral | SAC 9985 group | Section 194-H | 2.0% TDS (Finance Act 2024) | Form 16A / Form 131 (quarterly) |
Worked Corporate Invoice Example: ₹5.0 Lakh Corporate Conference
The calculation below details a compliant corporate invoice for a turnkey conference at a hotel that qualifies as specified premises (room value above ₹7,500 in the preceding year, or declared), under SAC 996331 at 18% with Section 194-C TDS withholding:
(Note: For non-specified independent venues, bundled catering is billed at 5% GST [2.5% CGST + 2.5% SGST = ₹25,000 tax], while Section 194-C 2% TDS remains unchanged on the taxable base value).
Reconciling Form 26AS / AIS and Form 16A with Venura OS
Venura streamlines corporate tax compliance:
- Automated TDS Deduction Tracking: Automatically flags whether corporate clients deducted 2% (194-C) or 10% (194-I), logging the tax credit in customer ledgers.
- Form 26AS Matching: Reconciles quarterly Form 16A certificates against TRACES portal ledgers, preventing uncredited tax disputes.
- One-Click Tally Prime Sync: Exports corporate sales journals and TDS receivable ledgers directly into Tally Prime.
Handling Mandatory E-Invoicing & IRN Generation for Corporate Invoices
For venue enterprises with annual aggregate turnover exceeding ₹5 Crores:
- 1Mandatory B2B E-Invoicing: Corporate event invoices must be uploaded to the Invoice Registration Portal (IRP) to generate an Invoice Reference Number (IRN) and statutory signed QR code.
- 2Automated IRN Generation in Venura: Generates IRNs via authorized GST Suvidha Providers in real time, embedding government QR codes directly onto output PDFs.
- 3Input Tax Credit Guarantee: Validates corporate client GSTIN checksums to ensure zero tax credit discrepancies in GSTR-2B.
Vendor Master File & Form 16A TDS Certificate Audits
Ensuring corporate statutory compliance across all corporate clients:
- 1Corporate Master File Review: Verify active 15-digit GSTINs, corporate TAN details, and billing addresses for all regular corporate clients.
- 2Quarterly Form 16A TDS Reconciliation: Reconcile 2% Section 194-C TDS deductions against central TRACES portal ledgers, preventing tax filing penalties.
One-Click Tally Prime Sync for Corporate Invoices
Streamlining corporate event accounting workflows:
- Automated Sales & Purchase Ledgers: Export client tax invoices, vendor expense ledgers, and CGST/SGST splits directly into Tally Prime XML ledgers in under 60 seconds, eliminating manual data entry.
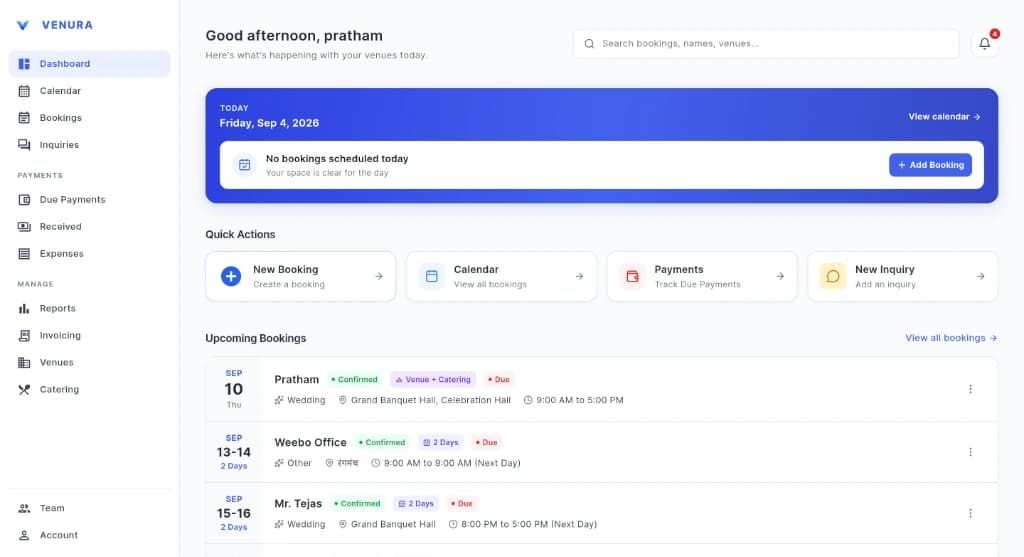
Venura prints the right SAC code, GST split and advance receipts on every banquet bill. See Venura venue management software.
SAC 996331 GST Invoice Generator
Generate compliant GST invoices (5% for bundled catering, 18% for hall-only rentals and specified premises) and manage corporate TDS deductions in real time.
Sumeet Yadav
Co-Founder & CTO, Venura
Systems architect specializing in GST compliance automation, Tally Prime ledger synchronisation, and enterprise financial access control for Indian hospitality and catering enterprises.
Frequently asked questions
What is the TDS rate on banquet hall booking for corporate events in India?
When a banquet hall provides a composite package of hall rental and food catering under SAC 996331, TDS is deducted at 2.0% under Section 194-C (Contract for Catering) in accordance with CBDT Circular No. 05/2002. If pure space is rented without food, 10% TDS applies under Section 194-I, but only when the rent is more than ₹50,000 for the month. For payments from 1 April 2026 both are covered by Section 393(1) of the Income-tax Act 2025, at the same rates.
What does CBDT Circular No. 05/2002 state regarding banquet hall TDS?
CBDT Circular No. 05/2002 clarifies that where a hotel or banquet hall enters into an agreement with a client to provide facilities including meals/catering for a conference or event, the contract is a contract for catering/work and attracts TDS under Section 194-C, not Section 194-I.
Is TDS calculated on the GST component of the banquet invoice?
No. Under CBDT Circular No. 23/2017, TDS under the Income Tax Act is deducted strictly on the taxable value of services, excluding the GST component, provided the GST is indicated separately on the tax invoice.
How does venue management software track corporate TDS deductions?
Venura OS automatically calculates Section 194-C (2%) or 194-I (10%) TDS deductions on corporate invoices, manages Form 16A certificate reconciliation, and syncs directly with Tally Prime.
This article is general information, not tax or legal advice. Rules and rates change, so confirm with your chartered accountant or the official notification before you bill.
Put These Systems to Work in Venura Venue OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.