GST on Banquet Hall: Rate, SAC Code & Tax Rules for Indian Venue Owners (2026 Guide)
Co-Founder & CTO, Venura
Stop double bookings, manage hall calendars & automate GST bills.
Venura Venue OS unifies multi-hall booking calendars, token advances, and Tally Prime ledgers in real time.
GST on Banquet Hall: Rate, SAC Code & Tax Rules for Indian Venue Owners (2026 Guide)
Statutory Classification: Pure Hall Lease (18%) vs Bundled Catering (5% vs 18%)
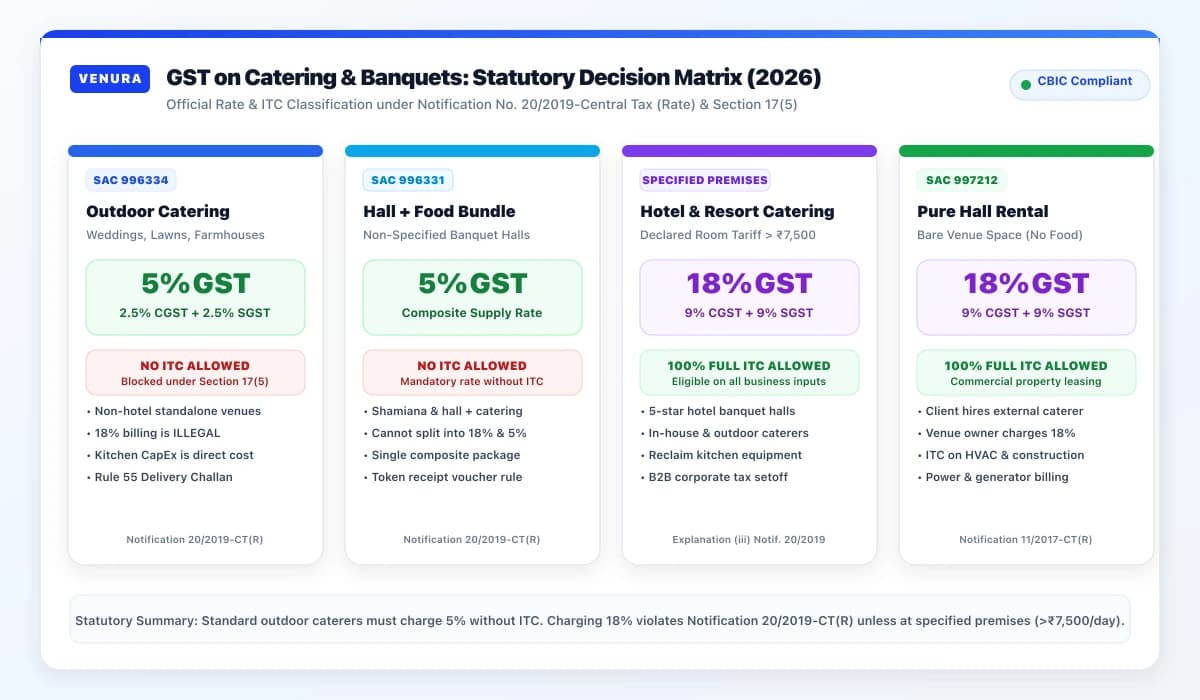
Under the Central Goods and Services Tax (CGST) framework, the tax rate for banquet venue services is determined by whether food is bundled and whether the property constitutes 'specified premises':
When a banquet hall, party plot, or marriage lawn leases only the physical real estate space (ballroom, stage, lawn, air conditioning, and electrical power) and the client hires an external third-party caterer, the supply is classified as Renting of Immovable Commercial Property under SAC 997212. It attracts 18% GST (9% CGST + 9% SGST or 18% IGST), and the venue owner is entitled to 100% Input Tax Credit on civil repairs, HVAC maintenance, furniture CapEx, and generator fuel.
Under Notification No. 20/2019-Central Tax (Rate) (Entry 7, item (v)), when a standalone banquet hall, club, or shamiana provides a composite supply of outdoor catering together with renting of premises, it attracts a mandatory 5% GST rate without Input Tax Credit (2.5% CGST + 2.5% SGST).
If the banquet facility is operated by or located within a hotel or resort where any unit of accommodation has a declared tariff exceeding ₹7,500 per day, the bundled service attracts 18% GST with full Input Tax Credit under Notification 20/2019.
Turnkey event design, floral mandap fabrication, stage trussing, and AV coordination billed by event management agencies attract 18% GST.
The 5 Most Dangerous Tax Violations in Banquet Invoicing
Indian GST intelligence directorates regularly penalize banquet operators for five common billing errors:
- 1. Illegal Rate Splitting to Evade Composite Supply Rules: Artificially splitting a single bundled wedding package into 18% hall rent and 5% food to bypass tax rules. Section 8 of the CGST Act mandates that composite supplies must be taxed as a single unified service.
- 2. Unreported Advance Booking Tokens: Failing to issue a formal Receipt Voucher under Section 31(3)(d) upon collecting booking advances. GST liability arises on the date the advance token is received, not on the event date.
- 3. Charging GST on Refundable Security Deposits: Security deposits collected purely to cover potential property breakage are non-taxable deposits. GST is charged only if a portion of the deposit is forfeited post-event.
- 4. Omitting Client GSTIN on Corporate B2B Invoices: Corporate clients require valid 15-digit GSTIN details and correct state codes to claim ITC in their GSTR-2B.
- 5. Improper Input Tax Credit (ITC) Claims on 5% Bundled Packages: Claiming ITC on kitchen equipment or commercial inputs when operating under the mandatory 5% non-specified catering rate is prohibited under Section 17(5).
Step-by-Step Worked Invoice Calculations: Pure Space vs Bundled Event
To ensure audit-proof accounting, venue operators must distinguish between two standard contracting formats:
### Model A: Pure Banquet Space Rental Invoice (SAC 997212 @ 18% GST with Full ITC)
For an evening wedding reception where the client hires an outside caterer:
(Venue owner claims 100% ITC on AC chillers, facility repairs, and commercial maintenance).
### Model B: Bundled Hall + Food Catering Invoice at Non-Specified Venue (SAC 996331 @ 5% GST No ITC)
For an all-inclusive wedding package at an independent marriage lawn:
(Mandatory 5% rate under Notification 20/2019; no ITC claimable on food inputs).
AC vs Non-AC Banquet Halls & Marriage Lawns
A frequent point of confusion among venue owners is whether non-air-conditioned banquet halls or open-air marriage lawns enjoy a lower tax rate:
- 1Uniform Application of Notification 20/2019: Under current GST law, tax rates do not distinguish between AC and non-AC facilities. Pure hall rentals attract 18% under SAC 997212, and bundled catering at non-specified venues attracts 5% under SAC 996331, whether air-conditioned or non-AC.
- 2Utility Submeter Pass-Through: If a banquet hall charges separately for electricity or generator diesel consumption as part of the venue rental contract, these utility charges form part of the composite supply and follow the tax rate of the principal supply.
Kalyana Mandapams, Community Halls & Charitable Trust Exemptions
Taxation rules for traditional marriage halls and charitable institutions:
- Commercial Kalyana Mandapams: Privately owned Kalyana Mandapams follow standard GST rules (18% for pure hall leasing under SAC 997212; 5% for bundled food packages under SAC 996331).
- Charitable Trust Exemption Threshold: Under Notification No. 12/2017-Central Tax (Rate) (Entry 10), renting of community halls or Kalyan Mandapams owned and managed by an entity registered under Section 12AA or 12AB of the Income Tax Act, 1961 is exempt from GST only if the daily rental fee is less than ₹10,000 per day.
- Breaching the ₹10,000 Cap: If a trust-owned community hall charges ₹10,000 or more per day, the entire rental amount becomes taxable at 18% GST with no partial exemption.
Automating Tax Compliance with Venura Venue OS
Venura provides an enterprise billing and taxation engine tailored for Indian banquet properties:
- Automated SAC & Tax Determination: Automatically applies SAC 997212 (18% pure lease) or SAC 996331 (5% bundled package / 18% specified premises) based on booking parameters.
- 3-Tier Payment Ledger: Tracks booking tokens, milestone advances, and final balances with automated Section 31(3)(d) GST Receipt Vouchers.
- Instant WhatsApp PDF Invoicing: Sends digitally signed, branded tax invoices directly to clients on WhatsApp with UPI QR payment links.
- Tally Prime Direct XML Integration: Exports clean monthly sales journals and tax ledgers for effortless GSTR-1 and GSTR-3B tax filing.
SAC 997212 / 996331 GST Invoice Generator
Generate compliant 18% pure lease and 5% bundled banquet invoices with advance receipt voucher deductions.
Sumeet Yadav
Co-Founder & CTO, Venura
Systems architect specializing in GST compliance automation, Tally Prime ledger synchronisation, and enterprise financial access control for Indian hospitality and catering enterprises.
Common Operational Questions
What is the exact SAC code for banquet hall services in India?
When pure hall space is rented without food, it falls under SAC 997212 (18% GST with full ITC). When banquet hall space is bundled with catering at non-specified venues, it falls under SAC 996331 (5% GST without ITC under Notification 20/2019). At specified hotel premises (>₹7,500 room tariff), bundled banquet catering attracts 18% GST with full ITC.
Is GST different for AC and Non-AC banquet halls?
No. Under current GST law, banquet halls and marriage lawns follow uniform tax rates regardless of whether the premises are air-conditioned, fan-cooled, or an open lawn.
What is the GST rate for Kalyana Mandapam booking in South India?
Commercial Kalyana Mandapams attract standard GST rates (18% for pure hall leasing; 5% for bundled food packages). Halls operated by registered charitable trusts under Section 12AA/12AB are exempt only if the daily rental tariff is under ₹10,000 per day. Any booking of ₹10,000/day or higher attracts full 18% GST.
Can a banquet hall operator register under the GST Composition Scheme?
Commercial banquet halls leasing real estate space cannot opt for the 5% restaurant composition scheme under Section 10(1). They must register as regular taxpayers.
How should a venue handle GST if a client cancels a booking after paying an advance token?
If an advance booking is cancelled and the token is refunded, the venue issues a formal Credit Note under Section 34 of the CGST Act referencing the original Receipt Voucher. This allows the venue to adjust the previously declared tax liability in GSTR-1. If the token is forfeited, it remains taxable.
Can corporate B2B clients claim 100% Input Tax Credit on banquet invoices?
Yes. Corporate entities booking banquet halls for legitimate business events (such as AGMs, dealer conferences, product launches, or training seminars) are entitled to claim full 100% Input Tax Credit on commercial hall rental invoices (SAC 997212 @ 18%), provided their valid 15-digit GSTIN is recorded.
Put These Systems to Work in Venura Venue OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.