GST on Catering Services: Rates, SAC Code & Invoicing Guide for Indian Caterers (2026)
Co-Founder & CTO, Venura
Build tiered menu packages, 1-tap WhatsApp quotes & track due payments.
Venura Catering OS replaces kitchen chaos with automatic menu portioning, zero-loss advance tracking, and WhatsApp billing.
GST on Catering Services: Rates, SAC Code & Invoicing Guide for Indian Caterers (2026)
The Core Regulatory Premise: 5% GST Without ITC Under Notification 20/2019
A widespread myth in the Indian event industry is that outdoor catering automatically attracts an 18% GST rate with full Input Tax Credit (ITC). Statutory tax law establishes the exact opposite:
Under Notification No. 20/2019-Central Tax (Rate) (effective 1st October 2019), the GST Council amended entry 7 of Notification No. 11/2017-CT(R). It specifically reduced the rate for outdoor catering from 18% with ITC down to 5% GST without ITC (2.5% CGST + 2.5% SGST for intra-state supplies, or 5% IGST for inter-state supplies).
When an independent caterer prepares, delivers, and serves food at a private residence, wedding lawn, farmhouse, community hall, or commercial office, the supply is classified under SAC 996334 and must mandatorily be billed at 5% GST with zero ITC.
Caterers cannot arbitrarily choose to pay 18% in order to reclaim input tax on equipment. Unless operating within 'specified premises', charging 18% violates Notification 20/2019 and will result in scrutiny notices, disallowance of customer ITC, and audit penalties under Section 73/74.
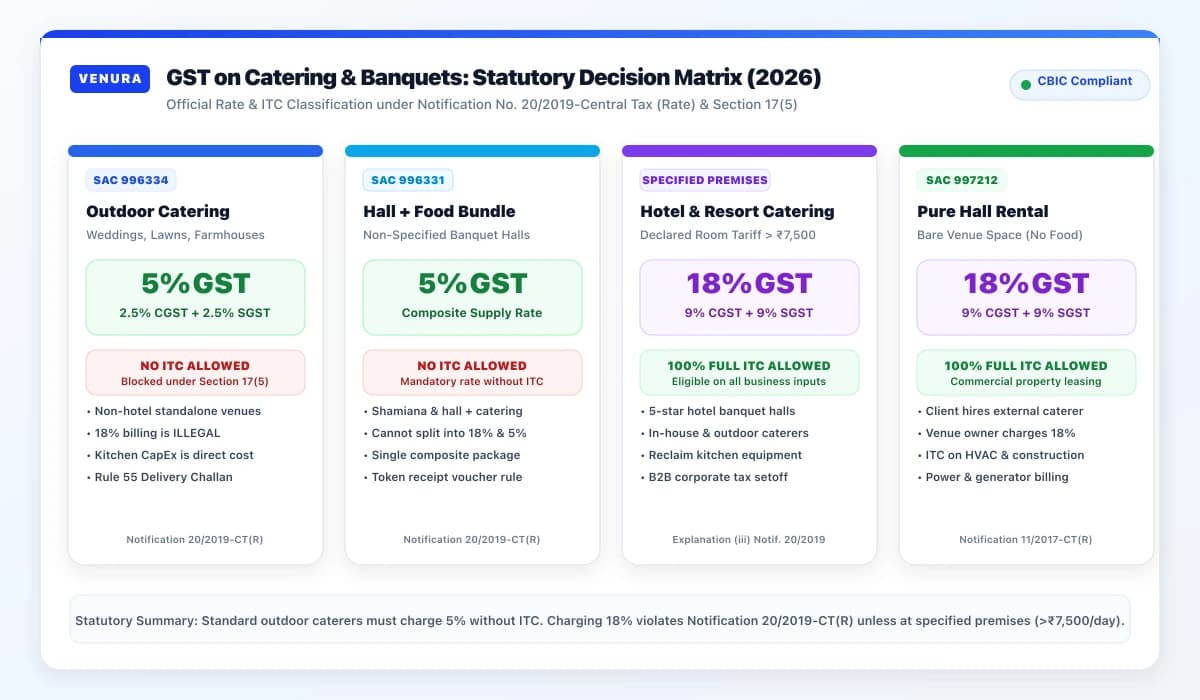
Catering GST Rates & SAC Classification Master Matrix
The statutory decision matrix below details the exact GST rates, SAC classifications, and Input Tax Credit eligibilities across all food service categories under current GST Council notifications:
| Food Service Category | Statutory SAC Code | Applicable GST Rate | Input Tax Credit (ITC) Status | Primary Legal Reference |
|---|---|---|---|---|
| Outdoor Event Catering (Weddings/Parties at non-hotel venues) | SAC 996334 | 5.0% (2.5% CGST + 2.5% SGST) | No ITC Allowed (Blocked under Sec 17(5)) | Notification No. 20/2019-CT(Rate) |
| Banquet Hall + Food Bundle (Non-specified premises) | SAC 996331 | 5.0% (2.5% CGST + 2.5% SGST) | No ITC Allowed (Mandatory 5% rate) | Notification No. 20/2019-CT(Rate) |
| Standalone Restaurant Dining (No hotel rooms) | SAC 996331 | 5.0% (2.5% CGST + 2.5% SGST) | No ITC Allowed (Except on output tax) | Notification No. 46/2017-CT(Rate) |
| Catering / Restaurant at Specified Premises (Room Tariff > ₹7,500/day) | SAC 996331 / 996334 | 18.0% (9% CGST + 9% SGST) | Full ITC Allowed on all commercial inputs | Notification No. 20/2019-CT(Rate) |
| Pure Banquet Hall Space Rental (No food supplied) | SAC 997212 | 18.0% (9% CGST + 9% SGST) | Full ITC Allowed (Commercial property lease) | Notification No. 11/2017-CT(Rate) |
| Contract Industrial / Corporate Canteen | SAC 996337 | 5.0% (2.5% CGST + 2.5% SGST) | No ITC Allowed to caterer | Circular No. 28/02/2018-GST |
The 'Specified Premises' Exception: When Does 18% GST Apply?
The only scenario where outdoor catering or banquet food services attract an 18% GST rate with full Input Tax Credit is at 'Specified Premises':
Under Explanation (iii) of Notification No. 20/2019-CT(Rate), 'specified premises' means premises providing hotel accommodation services having a declared tariff (or value of supply) of any unit of accommodation above ₹7,500 per unit per day or equivalent.
If a 5-star hotel or luxury resort with room tariffs exceeding ₹7,500 hosts a banquet or provides outdoor catering, the supply is taxable at 18% (9% CGST + 9% SGST or 18% IGST) with full 100% ITC on kitchen inputs, decor, and maintenance.
When an independent caterer provides catering at a venue located within specified premises, the service falls into the 18% tax bracket with ITC eligibility. However, once that same caterer serves at an independent farmhouse or private lawn, the rate drops back to the mandatory 5% without ITC.
Input Tax Credit (ITC) Rules: Blocked Credits Under Section 17(5)
Because independent caterers operate in the mandatory 5% GST bracket, stringent Input Tax Credit restrictions apply:
- ITC is Blocked on All Business Inputs: Under condition (b) of Notification No. 11/2017-CT(R) (as amended by Notification 20/2019-CT(R)) read with Section 17(5) of the CGST Act, caterers paying 5% tax cannot claim any ITC on:
- Commercial kitchen machinery (tandoors, dough kneaders, walk-in chillers, deep freezers).
- Tableware, chafing dishes, melamine crockery, and crystal glassware.
- Commercial LPG cylinders (19kg refills) and diesel for delivery trucks.
- Raw grocery ingredients (spices, dairy, packaging).
- Professional software licenses, CRM subscriptions, and digital billing systems.
Because input GST cannot be reclaimed against output liability, all GST paid on capital equipment and commercial inputs becomes a direct operational cost. Caterers must build these input taxes into their per-plate pricing strategy.
Corporate clients hiring caterers for corporate parties, employee lunches, or social events generally cannot claim ITC on food and beverages under Section 17(5)(b)(i), unless an outward taxable supply of the same category is made or provision of food is statutorily mandated under the Factories Act, 1948 (for factories with over 250 workers).
Worked Tax Invoice: Compliant ₹7.5 Lakh Wedding Feast at 5% GST
The worked calculation below demonstrates a fully compliant tax invoice for an independent 600-PAX wedding catering order in Jaipur, Rajasthan, operating under the statutory 5% GST rate (SAC 996334):
- Royal Marwari & Mughlai Multi-Course Buffet (600 PAX @ ₹950/plate): ₹5,70,000.00
- Live Delhi Chaat & Tandoori Starter Stations (3 Counters): ₹45,000.00
- Artisanal Jalebi-Rabdi & Live Kulfi Dessert Stations: ₹35,000.00
- Bone China Tableware, Cutlery & 24 Uniformed Stewards: ₹30,000.00
- Total Taxable Value (SAC 996334): ₹6,80,000.00
- Central GST (CGST @ 2.5%): ₹17,000.00
- State GST (SGST @ 2.5%): ₹17,000.00
- Gross Invoice Total (5.0% Total GST): ₹7,14,000.00
- Less Advance Token Received (Receipt Voucher #RV-089): -₹2,50,000.00
- Net Balance Due on Event Day: ₹4,64,000.00
(Statutory Note: Billing this order at 18% would be legally erroneous and expose the caterer to customer disputes and GST Department audit scrutiny under Notification 20/2019).
| Line Item Description | SAC Code | Taxable Amount (₹) | CGST Rate | SGST Rate | Total Tax (₹) |
|---|---|---|---|---|---|
| Royal Wedding Buffet (600 PAX) | 996334 | ₹5,70,000.00 | 2.5% | 2.5% | ₹28,500.00 |
| Live Starter Counters (3 Stations) | 996334 | ₹45,000.00 | 2.5% | 2.5% | ₹2,250.00 |
| Dessert Stations & Live Kulfi | 996334 | ₹35,000.00 | 2.5% | 2.5% | ₹1,750.00 |
| Crockery, Glassware & Steward Service | 996334 | ₹30,000.00 | 2.5% | 2.5% | ₹1,500.00 |
| Total Summary | SAC 996334 | ₹6,80,000.00 | 2.5% (₹17k) | 2.5% (₹17k) | ₹34,000.00 |
Bundled Banquet Space + Food: Composite Supply Rules
A critical area clarified by Notification No. 20/2019-Central Tax (Rate) is the bundling of event premises with catering:
When a banquet hall, party plot, or marriage lawn supplies venue rental bundled together with catering services (food and beverages), it forms a composite supply under Section 2(30) of the CGST Act. Notification No. 20/2019-CT(R) brought composite supply of outdoor catering together with renting of premises (convention halls, clubs, shamianas) at non-specified venues under the mandatory 5% GST rate without ITC.
If an event space leases only the bare hall or lawn without any food, beverages, or kitchen services, the transaction is pure renting of immovable property under SAC 997212. It attracts 18% GST (9% CGST + 9% SGST) and allows the venue owner to claim full Input Tax Credit on facility maintenance, civil construction materials, and furniture CapEx.
Attempting to artificially bifurcate an integrated wedding package into 18% hall rent and 5% food to bypass tax rules will be recharacterized as a composite supply during GST departmental audits under Section 8.
Managing Composition Scheme (Section 10) vs Regular Scheme
Understanding the tax compliance paths available to catering entrepreneurs:
Handling E-Way Bills & Delivery Challans (Rule 55)
Moving commercial food and catering equipment across locations involves clear statutory rules:
Freshly prepared hot meals, buffet items, and cooked food transported to an event venue are exempt from E-Way bill generation under Rule 138(14) of the CGST Rules, 2017.
Transporting commercial tandoors, chafing dishes, gas burners, bone china crockery, and portable chillers requires a formal Delivery Challan under Rule 55.
Venura Catering OS automatically generates Rule 55 compliant Delivery Challans on mobile, ensuring transport vehicles pass state GST border checks without delay.
Direct Accounting Integration with Tally Prime
Venura automates compliance for catering enterprises:
- Accurate 5% / 18% Rule Application: Auto-assigns the correct SAC code (996334 for outdoor catering, 996331 for banquet packages) and accurately computes 2.5% CGST + 2.5% SGST splits without human error.
- Section 31(3)(d) Advance Voucher Management: Automatically references booking token advances and deducts them from final invoices.
- One-Click Tally Prime XML Sync: Exports complete sales journals, client debtor ledgers, and CGST/SGST tax entries directly into Tally Prime, eliminating manual accounting.
SAC 996334 / 996331 GST Invoice Generator
Generate compliant 5% and 18% GST catering invoices, delivery challans, and advance receipt vouchers in real time.
Sumeet Yadav
Co-Founder & CTO, Venura
Systems architect specializing in GST compliance automation, Tally Prime ledger synchronisation, and enterprise financial access control for Indian hospitality and catering enterprises.
Common Operational Questions
What is the GST rate for outdoor catering services in India?
Under Notification No. 20/2019-Central Tax (Rate), outdoor event catering (SAC 996334) at non-specified premises (farmhouses, lawns, private residences) is taxed at 5% GST (2.5% CGST + 2.5% SGST) without Input Tax Credit (ITC). It attracts 18% GST with full ITC only if supplied at 'specified premises' (hotels where declared room tariff exceeds ₹7,500/day).
Can an outdoor wedding caterer charge 18% GST to claim Input Tax Credit?
No. The 5% rate without ITC is mandatory under Notification No. 20/2019-CT(Rate) for caterers operating outside specified premises. Independent caterers cannot voluntarily opt to charge 18% GST to claim ITC on kitchen equipment or commercial inputs.
Can independent caterers claim Input Tax Credit (ITC) on commercial kitchen equipment or LPG?
No. Because outdoor catering is subject to the mandatory 5% tax bracket without ITC, Input Tax Credit on commercial kitchen equipment, chafing dishes, commercial LPG, vehicles, and software is blocked under Section 17(5) of the CGST Act.
What is the GST rate when banquet hall rental is bundled with catering?
When a banquet hall or party lawn provides hall rental bundled together with catering services at non-specified premises, it is treated as a composite supply taxed at 5% GST without ITC under Notification No. 20/2019-CT(Rate). If the hall is leased purely as vacant space without any food, it is classified under SAC 997212 at 18% GST with full ITC.
Do caterers need an E-Way bill to transport cooked food to a wedding lawn?
No. Fresh cooked meals and buffet dishes are exempt from E-Way bills under Rule 138(14). However, transporting commercial kitchen machinery, tandoors, and tableware requires a formal Delivery Challan issued under Rule 55 of the CGST Rules.
How does Venura Catering OS automate GST compliance for caterers?
Venura Catering OS applies statutory 5% (or 18% specified premises) tax splits, enforces correct SAC 996334 classifications, auto-adjusts Section 31(3)(d) advance receipt vouchers, generates Rule 55 delivery challans, and exports complete ledgers to Tally Prime.
Put These Systems to Work in Venura Catering OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.