SAC Code for Catering Services: 996331 vs 996334 Rules, Rates & ITC Eligibility (2026)
Co-Founder & CTO, Venura
Build tiered menu packages, 1-tap WhatsApp quotes & track due payments.
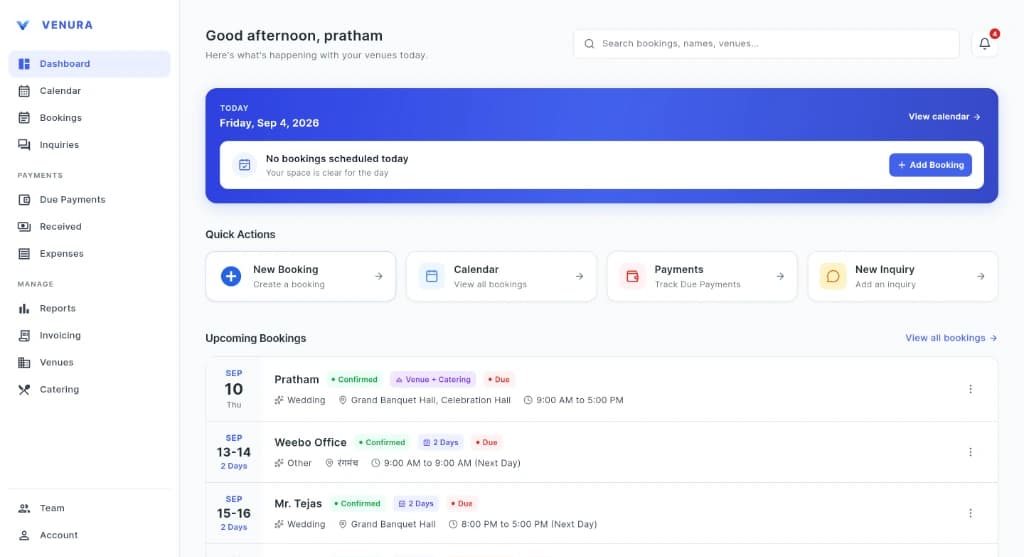
Venura Catering OS replaces kitchen chaos with automatic menu portioning, zero-loss advance tracking, and WhatsApp billing.
SAC Code for Catering Services: 996331 vs 996334 Rules, Rates & ITC Eligibility (2026)
The Master SAC Code Framework for Catering Services
Under Chapter 99 (Services), Heading 9963, Indian GST law categorizes food hospitality supplies into distinct statutory classifications:
When an independent caterer prepares, delivers, and serves food at a client's private residence, farmhouse, open lawn, or rented hall without owning the venue, it is classified under SAC 996334. Under Notification No. 20/2019-CT(Rate), it attracts 5% GST (2.5% CGST + 2.5% SGST or 5% IGST) with no Input Tax Credit allowed on business inputs.
When a banquet hall, party plot, or marriage lawn provides hall space bundled with food at non-specified venues, it is a composite supply taxed at 5% GST without ITC under Notification No. 20/2019-CT(Rate).
When catering is provided at or by hotels/resorts where declared room tariffs exceed ₹7,500 per unit per day, the supply attracts 18% GST (9% CGST + 9% SGST) with full Input Tax Credit.
Leasing bare venue premises without any food or beverages is classified as commercial leasing under SAC 997212, taxed at 18% GST with full ITC.
Food supplied in corporate canteens attracts 5% GST without ITC.
SAC Code, Tax Rate & ITC Eligibility Comparison Table
The table below provides a statutory summary across all catering service categories under Notification No. 20/2019-CT(Rate):
| Catering Service Category | SAC Code | CGST Rate | SGST Rate | Total GST Rate | Input Tax Credit (ITC) Status |
|---|---|---|---|---|---|
| Outdoor Event Catering (Farmhouse / Lawn / Residence) | 996334 | 2.5% | 2.5% | 5.0% | Blocked (No ITC Allowed under Sec 17(5)) |
| Banquet Hall + Bundled Catering (Non-Specified) | 996331 | 2.5% | 2.5% | 5.0% | Blocked (No ITC Allowed under Notification 20/2019) |
| Catering at Specified Premises (Room Tariff > ₹7,500) | 996334 / 996331 | 9.0% | 9.0% | 18.0% | Full ITC Allowed on Commercial Inputs |
| Pure Banquet Hall Space Lease (No Food) | 997212 | 9.0% | 9.0% | 18.0% | Full Commercial ITC Allowed on Facility |
| Corporate Office Canteen Supply | 996337 | 2.5% | 2.5% | 5.0% | Blocked (No ITC Allowed to Caterer) |
| Standalone Restaurant Dining | 996331 | 2.5% | 2.5% | 5.0% | Blocked (No ITC Allowed under Notif. 46/2017) |
Input Tax Credit (ITC) Rules for Outdoor Caterers
Because independent outdoor caterers operate in the mandatory 5% GST bracket under SAC 996334, strict Input Tax Credit conditions apply:
- Blocked ITC under Section 17(5): Independent caterers paying 5% tax cannot claim any ITC on commercial kitchen equipment (tandoors, dough kneaders, deep freezers), chafing warmers, tableware, commercial LPG, or vehicle maintenance.
- ITC is an Operational Cost: Since input GST cannot be set off, caterers must incorporate the GST paid on ingredients and equipment into their gross food costing and package pricing.
- When is ITC Allowed?: Full ITC is allowed exclusively for catering services provided at 'specified premises' (>₹7,500 room tariff) where 18% GST is charged, or for pure commercial hall rentals under SAC 997212.
Worked Example: Compliant SAC 996334 Outdoor Catering Invoice (5% GST)
Here is a compliant tax invoice calculation for a 500-PAX wedding catering order at a private farmhouse in Pune, Maharashtra, under the statutory 5% rate:
- Confirmed Headcount: 500 PAX @ ₹750/plate = ₹3,75,000.00
- Live Counter Surcharge (Tawa Chaat & Dessert Counter): ₹45,000.00
- Crockery, Cutlery & Service Stewards: ₹30,000.00
- Total Taxable Value (SAC 996334): ₹4,50,000.00
- CGST (2.5% under SAC 996334): ₹11,250.00
- SGST (2.5% under SAC 996334): ₹11,250.00
- Gross Invoice Amount (5% GST): ₹4,72,500.00
- Less Advance Booking Token Adjusted (Receipt Voucher #RV-089): -₹1,50,000.00
- Net Balance Due on Event Day: ₹3,22,500.00
Automating SAC Classification with Venura Catering OS
Venura eliminates tax classification errors:
- Automatic SAC Selection: Detects whether the event is standard outdoor catering (SAC 996334 @ 5%), bundled venue package (SAC 996331 @ 5%), or specified premises hotel catering (18%), applying exact tax rules automatically.
- B2B GSTIN Checksum Verification: Validates client GST numbers in real time, preventing GSTR-1 filing rejections.
- One-Click Tally Prime Sync: Exports complete sales journals and tax ledgers directly into Tally Prime in under 60 seconds.
Handling Reverse Charge Mechanism (RCM) on Ancillary Catering Inputs
Catering businesses procuring supplies from unregistered vendors must comply with statutory Reverse Charge Mechanism (RCM) rules:
- 1Goods Transport Agency (GTA) Freight: When caterers hire unregistered commercial trucks to transport food containers and crockery to an outdoor lawn, GST on freight is payable under RCM at 5% (without ITC) or 12% under forward charge.
- 2Security & Valet Parking Services: Security personnel hired from non-corporate agencies for outdoor event venues attract 18% GST under RCM under Notification No. 29/2018-Central Tax (Rate).
- 3Maintaining RCM Self-Invoices: Under Section 31(3)(f) of the CGST Act, caterers must generate internal self-invoices for all RCM transactions.
SAC 996334 / 996331 GST Invoice Generator
Generate compliant 5% and 18% GST invoices for banquet and outdoor catering orders in real time.
Sumeet Yadav
Co-Founder & CTO, Venura
Systems architect specializing in GST compliance automation, Tally Prime ledger synchronisation, and enterprise financial access control for Indian hospitality and catering enterprises.
Common Operational Questions
What is the difference between SAC 996331 and SAC 996334?
SAC 996331 applies when catering is provided in-house at a banquet hall, hotel, or restaurant as part of a bundled facility package. SAC 996334 applies to independent outdoor catering delivered at client residences, open lawns, or external venues. Both are taxed at 5% GST without ITC at non-specified venues.
Can an outdoor wedding caterer charge 18% GST to claim ITC?
No. Under Notification No. 20/2019-Central Tax (Rate), outdoor catering at non-specified venues is mandatorily taxed at 5% GST without ITC. Caterers cannot voluntarily opt to charge 18% to claim ITC.
Can caterers claim Input Tax Credit on commercial cooking gas (LPG)?
No. Because outdoor catering is subject to the mandatory 5% tax bracket without ITC, Input Tax Credit on commercial LPG, kitchen equipment, and supplies is blocked under Section 17(5).
How does venue and catering software ensure GST compliance?
Venura OS auto-applies the correct SAC code, computes 2.5% CGST + 2.5% SGST splits, manages advance receipt voucher deductions under Section 31(3)(d), and exports Tally-compatible XML ledgers.
Put These Systems to Work in Venura Catering OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.