Reverse Charge Mechanism (RCM) on Banquet & Event Services in India (2026)
Co-Founder & CTO, Venura
Stop double bookings, manage hall calendars & automate GST bills.
Venura Venue OS unifies multi-hall booking calendars, token advances, and Tally Prime ledgers in real time.
Reverse Charge Mechanism (RCM) on Banquet & Event Services in India (2026)
The 5 Major RCM Categories Applicable to Banquet Venues
Under Section 9(3) and Notification No. 13/2017-Central Tax (Rate) (as amended up to 2026), venue operators must pay GST under RCM for five primary services:
Effective 10th October 2024 (notified under Notification No. 09/2024-Central Tax (Rate) following the 54th GST Council recommendation and refined by the 55th GST Council meeting), renting of commercial immovable property by any unregistered person to a registered person is subject to 18% GST under Reverse Charge (RCM). If your banquet hall, warehouse, or central base kitchen is rented from an unregistered individual or HUF landlord, your registered business must discharge 18% GST via the Electronic Cash Ledger and claim 100% Input Tax Credit (ITC) in Table 4(A)(3) of GSTR-3B.
Under Notification No. 29/2018-Central Tax (Rate), when security personnel or valet parking guards are supplied by any person other than a body corporate (such as a sole proprietorship or partnership firm) to a registered person, the registered banquet venue must pay 18% GST under RCM. If the security contractor is a body corporate (Private Limited, Public Limited, or Limited Liability Partnership / LLP), the service is taxable under Forward Charge, and the agency charges GST on its invoice.
When hiring transport trucks to move commercial tandoors, furniture, or pandal materials where the GTA does not charge 12% forward charge GST, the venue pays 5% GST under RCM.
Legal fees paid to individual advocates or law firms for commercial lease drafting, licensing, or municipal dispute resolution attract 18% GST under RCM.
When a corporate entity sponsors an event, conference, or awards gala hosted at the venue, the corporate sponsor pays 18% GST under RCM.
RCM Operational & Compliance Master Matrix
The table below summarizes RCM tax rates, statutory notifications, and ITC reclamation rules for banquet operators:
| Service Procured under RCM | Supplier Entity Type | Statutory RCM Tax Rate | Payment Mode Mandate | ITC Reclamation Status |
|---|---|---|---|---|
| Commercial Property Renting (Landlord) | Unregistered Individual / HUF | 18.0% (9% CGST + 9% SGST) | Mandatory Cash Ledger payment | 100% Reclaimable in same month GSTR-3B |
| Security & Valet Guard Personnel | Non-Corporate (Proprietor / Partnership) | 18.0% (9% CGST + 9% SGST) | Mandatory Cash Ledger payment | 100% Reclaimable in same month GSTR-3B |
| GTA Commercial Freight Transport | Unregistered / Registered GTA | 5.0% (2.5% CGST + 2.5% SGST) | Mandatory Cash Ledger payment | 100% Reclaimable in same month GSTR-3B |
| Advocate & Legal Consultancy | Individual Lawyer / Firm | 18.0% (9% CGST + 9% SGST) | Mandatory Cash Ledger payment | 100% Reclaimable in same month GSTR-3B |
| Corporate Sponsorship Rights | Corporate Enterprise | 18.0% (Integrated / Central Tax) | Paid by Corporate Sponsor | 100% Reclaimable by Sponsor in GSTR-2B |
| Commercial Property Rent from Govt | Local Municipality / Trust | 18.0% (SAC 997212) | Mandatory Cash Ledger payment | 100% Reclaimable in same month GSTR-3B |
The Golden Rule: RCM Must Be Paid in Electronic Cash
A critical compliance rule that trips up many banquet accountants:
- No ITC Offset for RCM Payment: Under Section 49(4) of the CGST Act, tax liability under Reverse Charge cannot be paid using existing Input Tax Credit balances; it MUST be discharged in cash via the Electronic Cash Ledger.
- Immediate 100% ITC Reclamation: Once the RCM cash liability is paid in GSTR-3B (Table 3.1(d)), the business is entitled to claim the exact same amount as Input Tax Credit in Table 4(A)(3) of the same month's return, resulting in zero net financial cost.
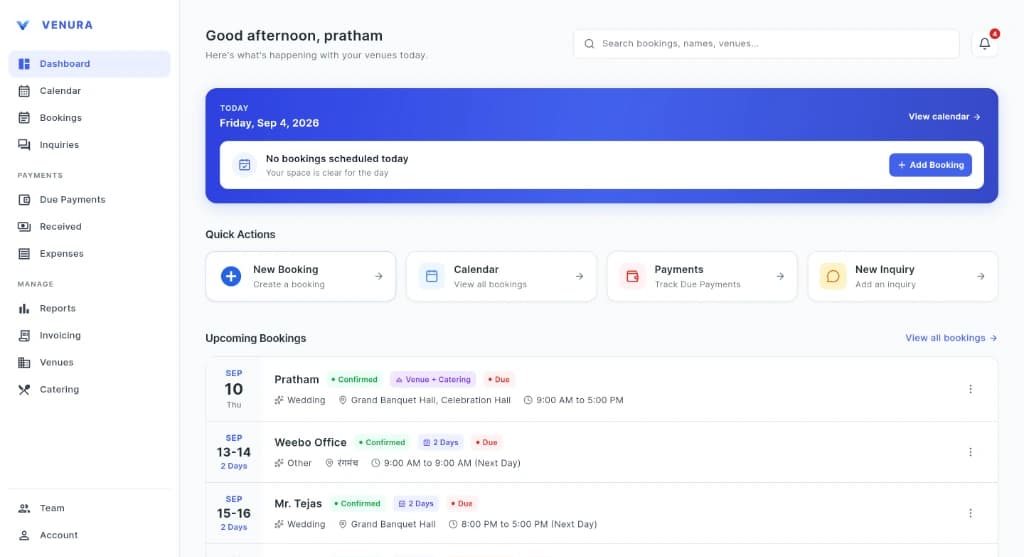
Automating RCM Accounting with Venura OS
Venura eliminates RCM compliance mistakes:
- Automated RCM Vendor Tagging: Identifies non-corporate security agencies and GTA freight invoices, auto-calculating RCM cash liabilities.
- One-Click Tally Prime Sync: Exports complete RCM journal entries and cash tax vouchers directly into Tally Prime in seconds.
Documenting Self-Invoicing under Section 31(3)(f)
Complying with statutory self-invoicing rules for RCM transactions:
- 1Mandatory Self-Invoice Generation: When procuring services from an unregistered vendor subject to RCM (e.g. an unregistered security contractor), the registered venue must issue a Self-Invoice under Section 31(3)(f).
- 2Consecutive Serial Numbering: Self-invoices must maintain an independent, unique serial numbering sequence.
- 3Venura Automated Self-Invoicing: Automatically generates compliant Section 31(3)(f) self-invoices and payment vouchers with one tap.
Reconciling RCM in Annual GST Audit (GSTR-9 & 9C)
Ensuring clean annual tax audits without audit penalties:
- 1Table 4G Reconciliation: Declare all inward RCM supplies in Table 4G of GSTR-9, matching total tax paid in cash with Table 4(A)(3) of GSTR-3B.
- 2Tally Prime XML Export: Venura exports dedicated RCM ledgers, ensuring 100% reconciliation between financial books and GSTN portal records.
Handling Composition Scheme Subcontractors & RCM Exclusions
Clarifying RCM applicability across different vendor types:
- Composition Dealers: Supplies from registered composition taxpayers do not attract RCM; the invoice is treated as an exempt Bill of Supply.
- Regular Taxpayers (18% Forward Charge): Services billed by regular corporate vendors are paid under forward charge with 100% ITC.
- Venura Vendor Expense Ledger: Automatically categorizes vendor invoices into Forward Charge, RCM, and Exempt supplies for clean tax filing.
SAC 996331 GST Invoice Generator
Generate compliant GST invoices and manage RCM tax ledgers in real time.
Sumeet Yadav
Co-Founder & CTO, Venura
Systems architect specializing in GST compliance automation, Tally Prime ledger synchronisation, and enterprise financial access control for Indian hospitality and catering enterprises.
Common Operational Questions
What is the Reverse Charge Mechanism (RCM) in GST for banquet halls?
RCM is a statutory mechanism where the recipient of a service (the banquet venue) is legally liable to pay GST directly to the government instead of paying it to the supplier, applicable to security guard services, GTA freight, and advocate legal fees.
Can RCM tax liability be paid using existing Input Tax Credit (ITC)?
No. Under Section 49(4) of the CGST Act, RCM tax liability must be discharged strictly through the Electronic Cash Ledger. However, the exact amount paid is immediately reclaimable as Input Tax Credit in Table 4(A)(3) of the same month's GSTR-3B.
What is the GST rate under RCM for security guard agencies?
Security services provided by non-corporate entities (proprietary firms, partnerships) attract an 18% GST rate under RCM (9% CGST + 9% SGST for intra-state or 18% IGST for inter-state).
How does venue management software assist in RCM compliance?
Venura OS automatically tags RCM vendor invoices, computes monthly cash liability figures for GSTR-3B Table 3.1(d), and synchronizes accounting journals with Tally Prime.
Put These Systems to Work in Venura Venue OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.