Bank Loans & MSME Financing for Banquet Hall Construction & Interior Fitouts (2026)
Co-Founder & CTO, Venura
Stop double bookings, manage hall calendars & automate GST bills.
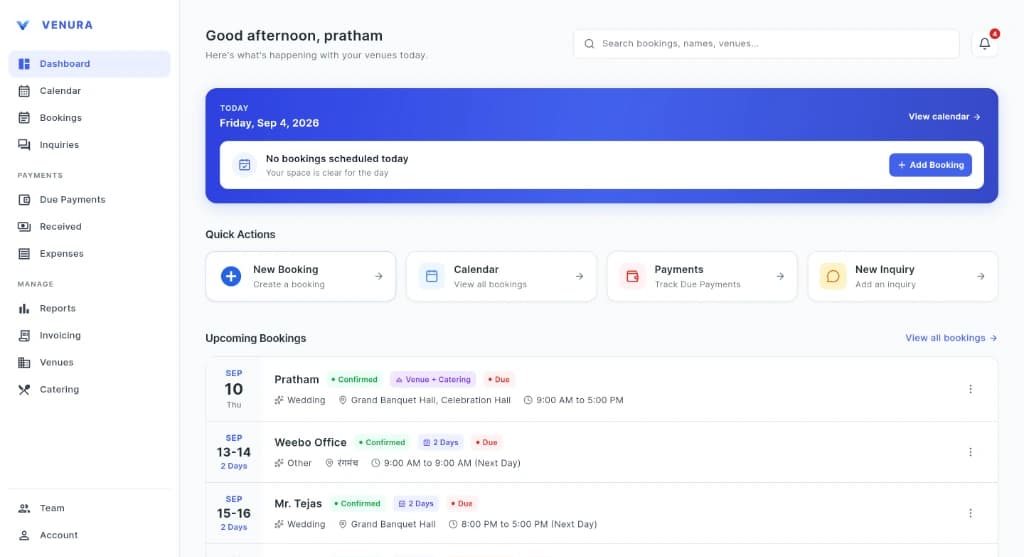
Venura Venue OS unifies multi-hall booking calendars, token advances, and Tally Prime ledgers in real time.
Bank Loans & MSME Financing for Banquet Hall Construction & Interior Fitouts (2026)
The 4 Primary Bank Financing Schemes for Indian Banquet Venues
Indian commercial banks (SBI, HDFC, ICICI, PNB, Bank of Baroda) offer four primary loan structures:
Under the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) scheme, registered MSME hospitality operators can secure term loans up to ₹2 Crores without requiring third-party collateral or personal property mortgages.
Standard 7 to 10-year commercial bank term loans covering 65% to 75% of total project CapEx (promoter contributes 25%–35% equity margin).
For established venues with long-term corporate master service agreements or multi-year advance booking cash flows, banks lend against the discounted net present value (NPV) of future lease receipts.
Dedicated low-interest asset-backed loans for commercial HVAC chillers, 250kVA diesel generator sets, and industrial kitchen equipment (3–5 year tenure).
Financial Metrics Required by Bank Loan Underwriters
Bank credit underwriting committees evaluate banquet loan proposals against four critical financial ratios:
| Financial Ratio / Metric | Minimum Bank Benchmark | Strong / Ideal Benchmark | Significance in Loan Approval |
|---|---|---|---|
| Debt Service Coverage Ratio (DSCR) | Minimum 1.35x | 1.75x – 2.25x | Measures operating cash flow ability to service annual loan EMI |
| Promoter Equity Margin Contribution | Minimum 25.0% | 30.0% – 35.0% | Skin in the game; promoter equity invested prior to loan disbursal |
| Interest Coverage Ratio (ICR) | Minimum 2.50x | 3.50x – 5.00x | Operating profit (EBIT) relative to annual interest obligations |
| Current Ratio (Liquidity) | Minimum 1.20 | 1.33 – 1.50 | Working capital liquidity to cover short-term operational liabilities |
| Loan Tenure & Moratorium | 5 – 7 Years | 7 – 10 Years + 6 mo moratorium | Allows venue construction without immediate EMI repayment pressure |
Essential Documents for Detailed Project Reports (DPR)
A successful banquet bank loan application requires submitting a certified Detailed Project Report containing:
- 1. Certified Architectural Plans & BOQ: Bill of Quantities (BOQ) certified by a registered chartered architect detailing civil, HVAC, electrical, and interior fitout costs.
- 2. Change of Land Use (CLU) & Municipal Approvals: Commercial land zoning approval, Town Planning sanctioned building drawings, and Fire Safety provisional NOC.
- 3. 5-Year Projected Financial Statements: Balance sheet, P&L, cash flow statements, and DSCR calculations certified by a Chartered Accountant (CA).
- 4. Advance Booking Track Record: Proves market demand via confirmed booking registers, tentative inquiries, and local wedding market survey data.
Accelerating Loan Payback with Venura Venue OS
Venura provides real-time financial tracking for bank debt management:
- Automated DSCR & Cash Flow Dashboards: Tracks monthly revenue, gross margins, and debt service coverage ratios in real time.
- One-Click Tally Prime Sync: Exports audited sales journals and tax ledgers, ensuring 100% compliance during annual bank financial audits.
Handling Interest Subventions & State Tourism Capital Subsidies
Leveraging government incentives for hospitality infrastructure:
- 1State Tourism Policy Capital Subsidies: Many Indian states (Rajasthan, Gujarat, UP, MP) offer 15% to 25% capital investment subsidies on new banquet and resort construction.
- 2MSME Interest Subvention Scheme: 2% per annum interest subvention on term loans for registered Udyam MSME enterprises.
- 3Accelerated Tax Depreciation: First-year 40% accelerated depreciation on solar rooftop plants and 15% on commercial HVAC plants under Section 32 of the Income Tax Act.
Building the 5-Year Projected Financial Model for Bank Underwriters
Structuring convincing financial projections in your Detailed Project Report (DPR):
- Realistic Occupancy Assumptions: Model 45 to 65 events in Year 1, scaling to 85+ events by Year 3 as community brand authority grows.
- Conservative Debt Service Coverage Ratio (DSCR > 1.75x): Demonstrates that projected net operating cash flows can easily service annual principal and interest repayments.
- Venura Financial Reports: Export audited historical P&L statements and confirmed advance booking ledgers directly into your DPR submission.
Collateral Property Valuation & Title Search Requirements
Preparing bank legal documentation for banquet property financing:
- 30-Year Clear Title Search Report: Banks require a certified 30-year non-encumbrance title search report from an empaneled bank advocate.
- Certified Commercial Property Valuation: Two independent valuations from approved bank valuation engineers assessing fair market value (FMV) and realisable value of commercial land and structures.
- Venura Financial Audits: Export audited historical P&L statements and confirmed advance booking ledgers directly into your loan appraisal file.
Event P&L & Vendor Expense Ledger
Track monthly operating cash flows, debt service coverage ratios (DSCR), and loan repayments.
Sumeet Yadav
Co-Founder & CTO, Venura
Systems architect specializing in GST compliance automation, Tally Prime ledger synchronisation, and enterprise financial access control for Indian hospitality and catering enterprises.
Common Operational Questions
What is the maximum loan amount available under the MSME CGTMSE scheme for a banquet hall?
Under the expanded CGTMSE scheme, eligible MSME hospitality businesses can secure up to ₹2 Crores (and up to ₹5 Crores in select government-backed programs) in collateral-free term loans for machinery, kitchen fitouts, and interior renovations.
What is the typical interest rate and tenure for a banquet hall construction loan in India?
Commercial bank term loan interest rates for hospitality properties range from 8.75% to 11.50% per annum, with repayment tenures of 7 to 10 years, often including a 6 to 12-month construction moratorium.
What is a good DSCR ratio for a banquet hall bank loan?
Banks look for a Debt Service Coverage Ratio (DSCR) of at least 1.35x, with 1.75x to 2.25x considered healthy. A DSCR of 1.75x means the venue generates ₹1.75 in net operating cash flow for every ₹1.00 of annual loan principal and interest repayment.
Can venue owners get bank loans against future confirmed wedding bookings?
Yes. Through Lease Rental Discounting (LRD) and Working Capital Advance schemes, banks provide credit against confirmed, non-cancellable client booking contracts and corporate master service agreements.
Put These Systems to Work in Venura Venue OS
Stop relying on fragile manual registers and Excel sheets. Run your entire booking pipeline, advance collection, and staff permissions on Venura.
Table of contents
Book a demo→
Get a personalized demo tailored to your use case.
Ready to modernize your event business?
Explore the Venura ecosystem or speak with our team.